Assuming a VA Loan: A Guide for Metro Atlanta Buyers
A Metro Atlanta REALTOR® on how a buyer takes over a seller's existing VA loan, and what a veteran selling a home should know before offering one
Some homes for sale carry an existing VA loan that a buyer can take over. In a VA loan assumption, the buyer takes on the seller's mortgage obligation and takes over what is still owed on that loan, known as the remaining balance. Ownership of the home transfers at closing.
The remaining balance is not the same thing as the sale price. It is the payoff amount left on the seller's existing loan. When a home sells for more than that payoff amount, the difference between the sale price and the remaining balance is a separate figure the buyer owes the seller at closing.
The VA treats the ability to assume the loan as a built-in feature of a VA-guaranteed loan. That makes it available to veterans and to buyers with no military service alike, and it is worth understanding before you consider a house that offers it.
Who can assume a VA loan
Any qualified buyer can assume a VA-guaranteed loan, including a buyer who is not a veteran. The buyer must meet the VA's credit and income standards, and the loan has to be current at closing. Before the assumption can be approved, the buyer also must be contractually committed to buying the home, and formally agree, through the assumption application submitted with the seller, to take on full responsibility for the loan.
A veteran buyer has one more option. An eligible veteran with enough entitlement who plans to live in the home can substitute their own entitlement for the seller's, which restores the seller's entitlement. That choice uses the buyer's own entitlement, so it is worth talking through with a VA-experienced lender before you write an offer.
Where to find homes with an assumable loan
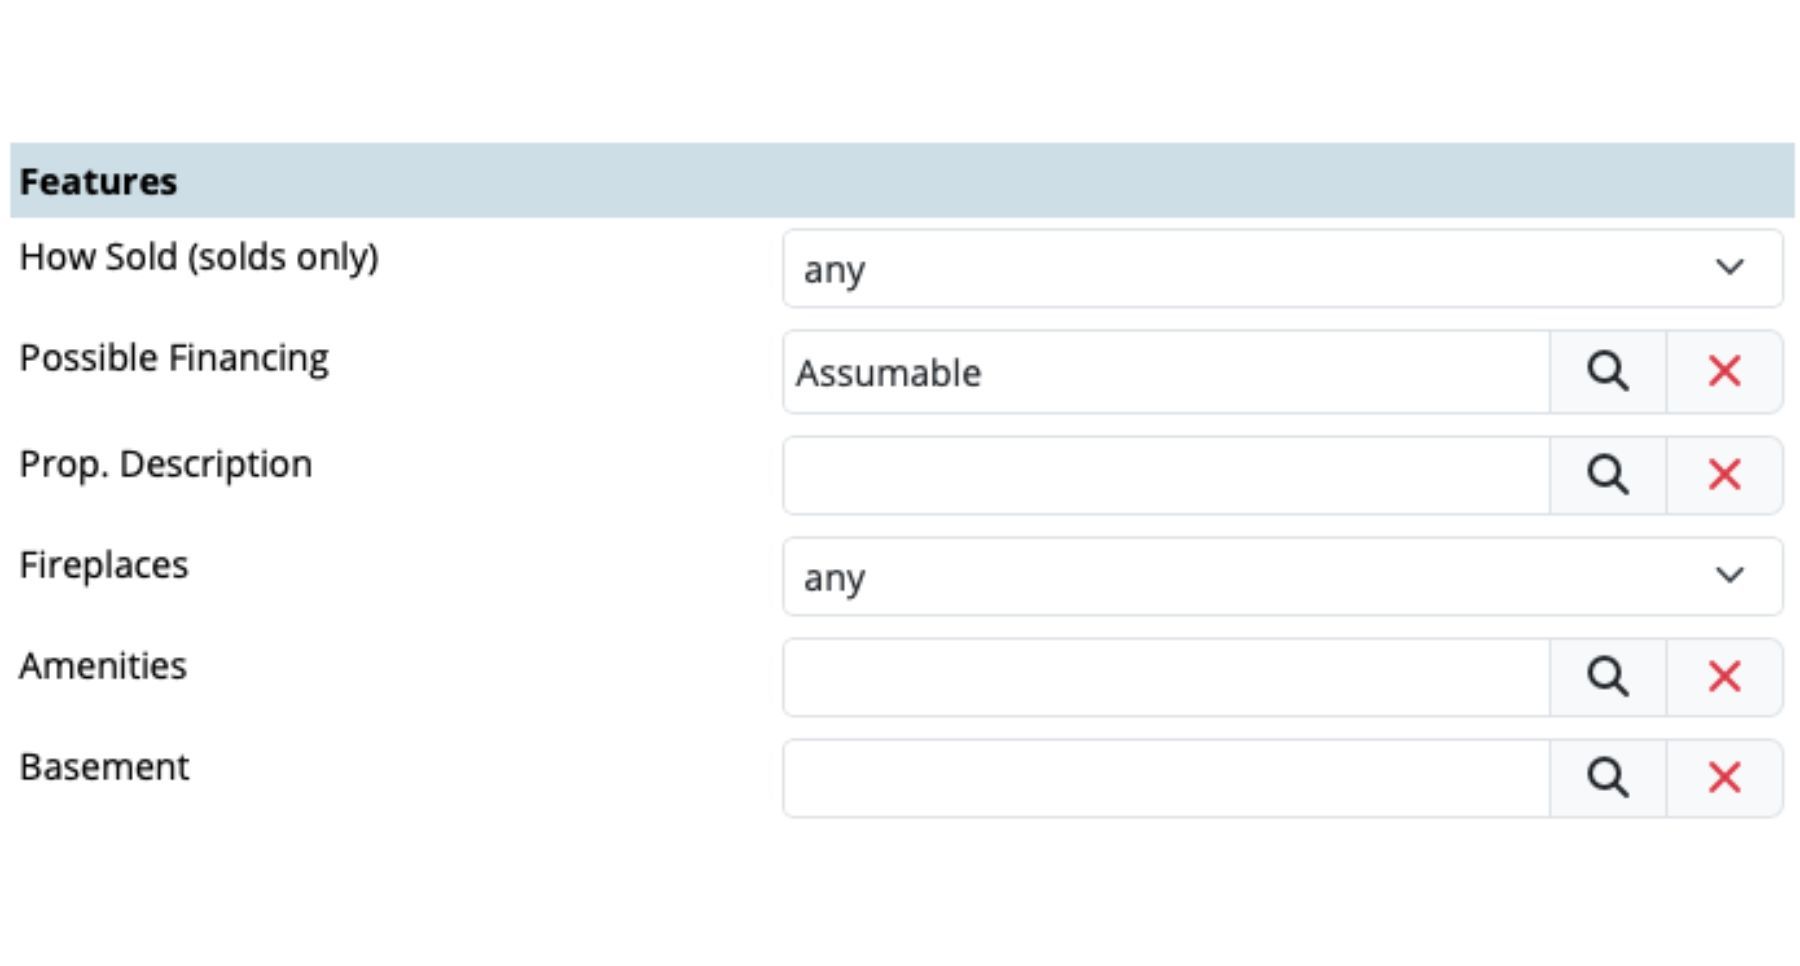
In the MLS systems that serve metro Atlanta, a listing can carry an assumable notation in the Terms field, and a search on that field is a good place to start. The notation does not say which type of loan can be assumed, so a listing marked assumable may or may not carry a VA loan.
The notation is also only as accurate as the information the listing agent entered. A home marked assumable may turn out not to be, and a home without the notation may still have a loan that can be assumed. Ask the listing agent to confirm the loan type with the seller and ask which company services the loan.
How the assumption gets approved
The company that services the seller's loan reviews the assumption, and the buyer and seller submit the application to that company. The documentation is the same as for a VA purchase loan. The VA has told servicers that a qualifying assumption cannot be turned down because of the servicer's own extra requirements, and the VA can take action when a servicer refuses to process one. If a servicer denies an assumption, the buyer or the seller can appeal the decision to the VA.
What a buyer pays at closing
That gap between the sale price and the remaining loan balance is the amount most often due the seller at closing on an assumption. The VA allows a second loan to cover that amount along with allowable closing costs, and the lender handles how that loan is set up. The VA also limits which other fees can be charged to a buyer who assumes a loan.
A VA funding fee applies to an assumption at a lower rate than on a new purchase loan. It is collected at closing and cannot be financed into the loan, and buyers who are exempt from the funding fee do not owe it. You can read more about how the VA funding fee works and who is exempt.
Questions to ask before you write an offer
Because the servicer will not review an assumption until the buyer already has a signed purchase contract, that contract should spell out how long the review is expected to take and what happens if the servicer does not approve it, including protecting the buyer's earnest money. These questions help you and your agent shape those terms:
- What type of loan does the seller have, and is it a VA loan?
- Which company services the loan, and is the loan current?
- Will the assumption include a substitution of entitlement, or will the seller's entitlement stay with the loan?
- What is the remaining balance on the loan, and how does that compare to the sale price? Any difference is what will be due the seller at closing.
- What does the contract say if the servicer does not approve the assumption?
A note for veterans selling a home with an assumable loan
If you are a veteran selling a home with a VA loan, an assumption is an option you can offer a buyer. A few points from the VA are worth knowing first.
When the servicer approves an assumption, you are no longer responsible for the mortgage payments on that loan. Your entitlement is a separate matter. If the buyer is not a veteran, your entitlement stays tied to the assumed loan until it is paid in full. If the buyer is an eligible veteran with enough entitlement who plans to live in the home and substitutes their entitlement for yours, your entitlement is then restored.
The VA expects your servicer to give you an acknowledgment form, VA Form 26-10291, as soon as an assumption application is received, and you sign it no later than closing. Your servicer or loan holder is also the one who obtains the buyer’s Certificate of Eligibility, to confirm the buyer has enough entitlement for a substitution. The form names four situations where a VA claim payment must be repaid in full before your entitlement can be restored: a foreclosure, a deed-in-lieu of foreclosure, a short-sale, or a VA loan acquisition on the assumed loan. Depending on how much entitlement you have used, you may still have some available for a new VA loan, and your lender or servicer can tell you how much. For more on how entitlement works over time, see how a veteran can use the VA benefit more than once.
Your next step
If you are looking at homes, I can search the MLS for listings marked assumable and help confirm the details with the listing agent before you write an offer. If you are selling, I can talk through how to describe the loan in your listing.
I am here when you are ready. I hope when the time comes, you will give me the chance to earn your trust.
Michelle Campbell | Campbell Group at Epique Realty | campbellgrouprealty.com
Categories
Recent Posts