Timing Your Move: What a Year Has Changed in North Metro Atlanta
For Anyone Comparing This October With Last October
If you have been thinking about a move and set it aside for a year, here is what that year changed. Buyers have more homes to choose from, prices are close to where they were, and the mortgage rate is what has shifted. This is how things stand now compared with a year ago across six north metro Atlanta counties, using FMLS (First Multiple Listing Service) market data and Freddie Mac's weekly mortgage rate survey.
More Homes to Choose From
Active listings are up in all six counties compared with October 2025, by 8% to 12%. The good news is that homes are still selling. About 20,000 single-family homes closed across the six counties in the 12 months ending September 2026, about 2% more than the year before.
FMLS also reports months of inventory, which estimates how long it would take to sell every home now listed at the current pace of sales. In September that figure ran from 4 to 6 months across the six counties, compared with 3 to 5 months a year earlier. For a buyer, that means more to look at. Counties are listed alphabetically below.
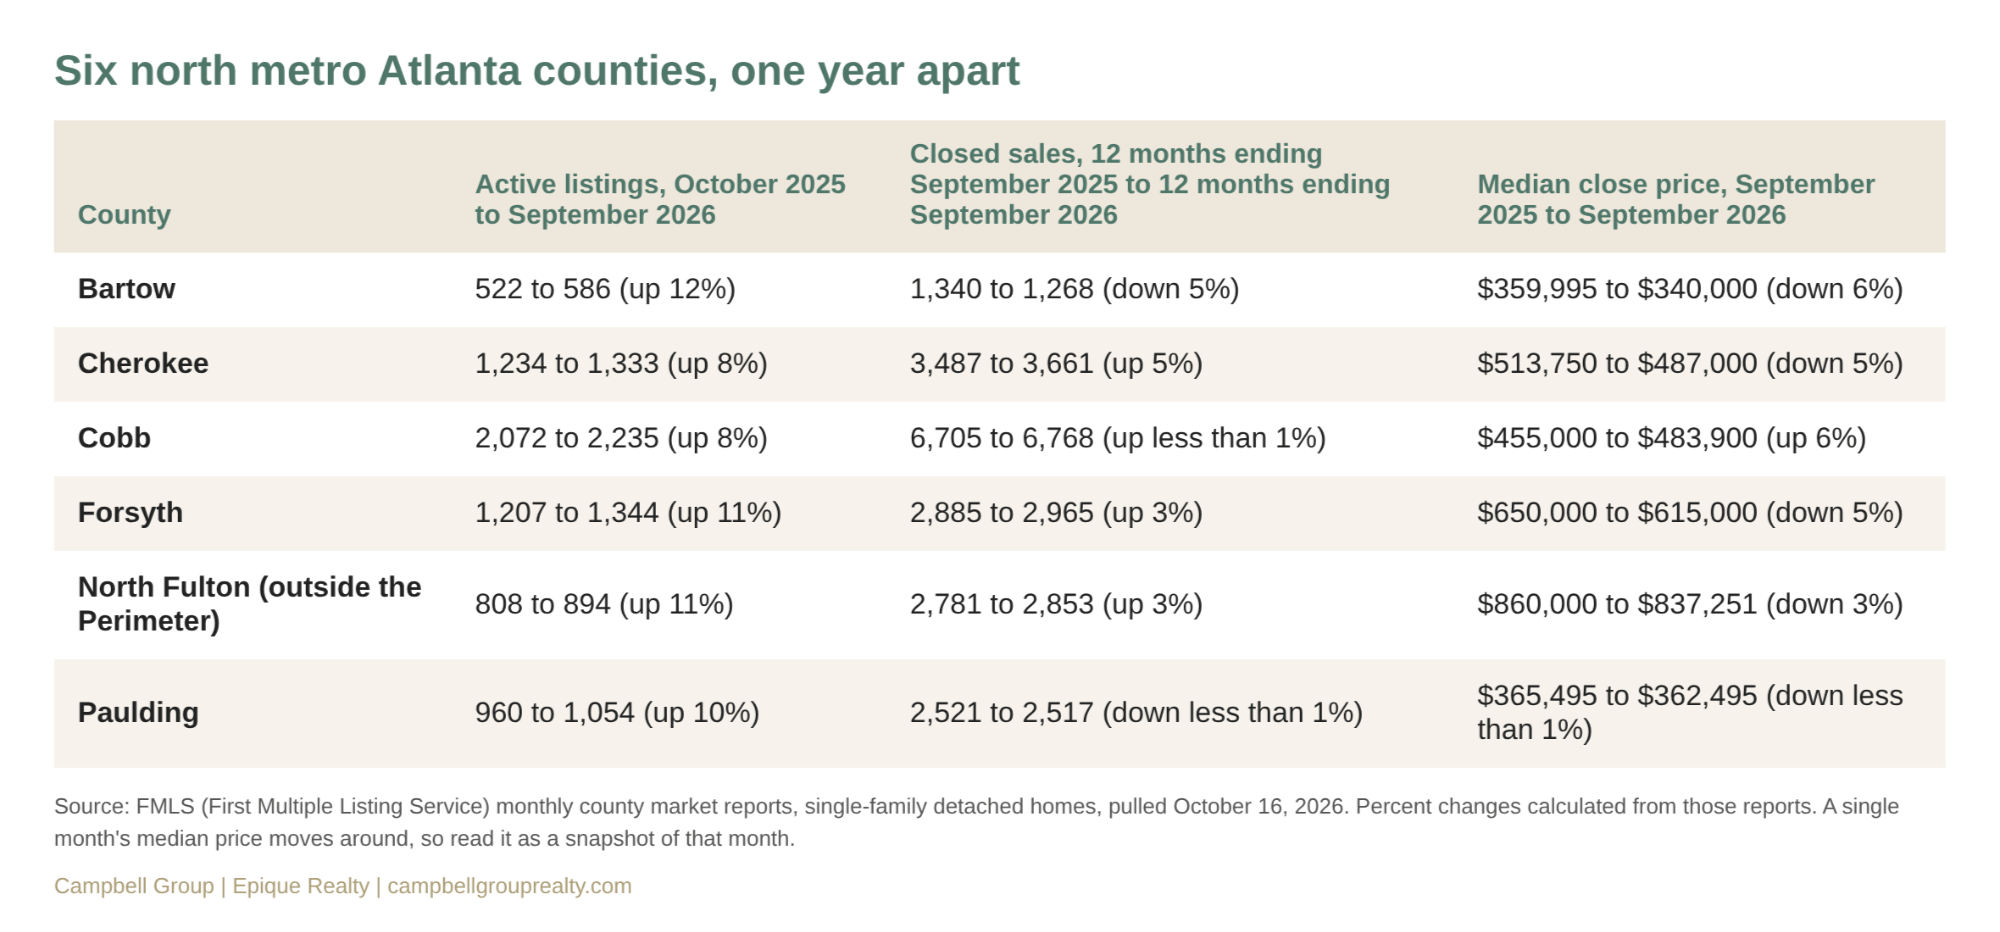
Prices Have Stayed Close to Where They Were
In September, the median price of a home that closed was lower than a year earlier in five of the six counties, by amounts ranging from under 1% to about 6%, and higher in Cobb by about 6%. A single month's median moves around, so it is best read as a snapshot of that month.
Each county has its own mix of homes, which is why prices differ from one county to the next. The numbers are most useful for comparing a county with its own past.
Mortgage Rates Are the Piece That Moved
The mortgage rate is where the year looks different. Freddie Mac's survey put the average 30-year fixed rate at 7.40% on October 15, 2026, up from 6.27% a year earlier and the highest weekly average of the past two years.
Here is the path, quarter by quarter, as an average of Freddie Mac's weekly readings:
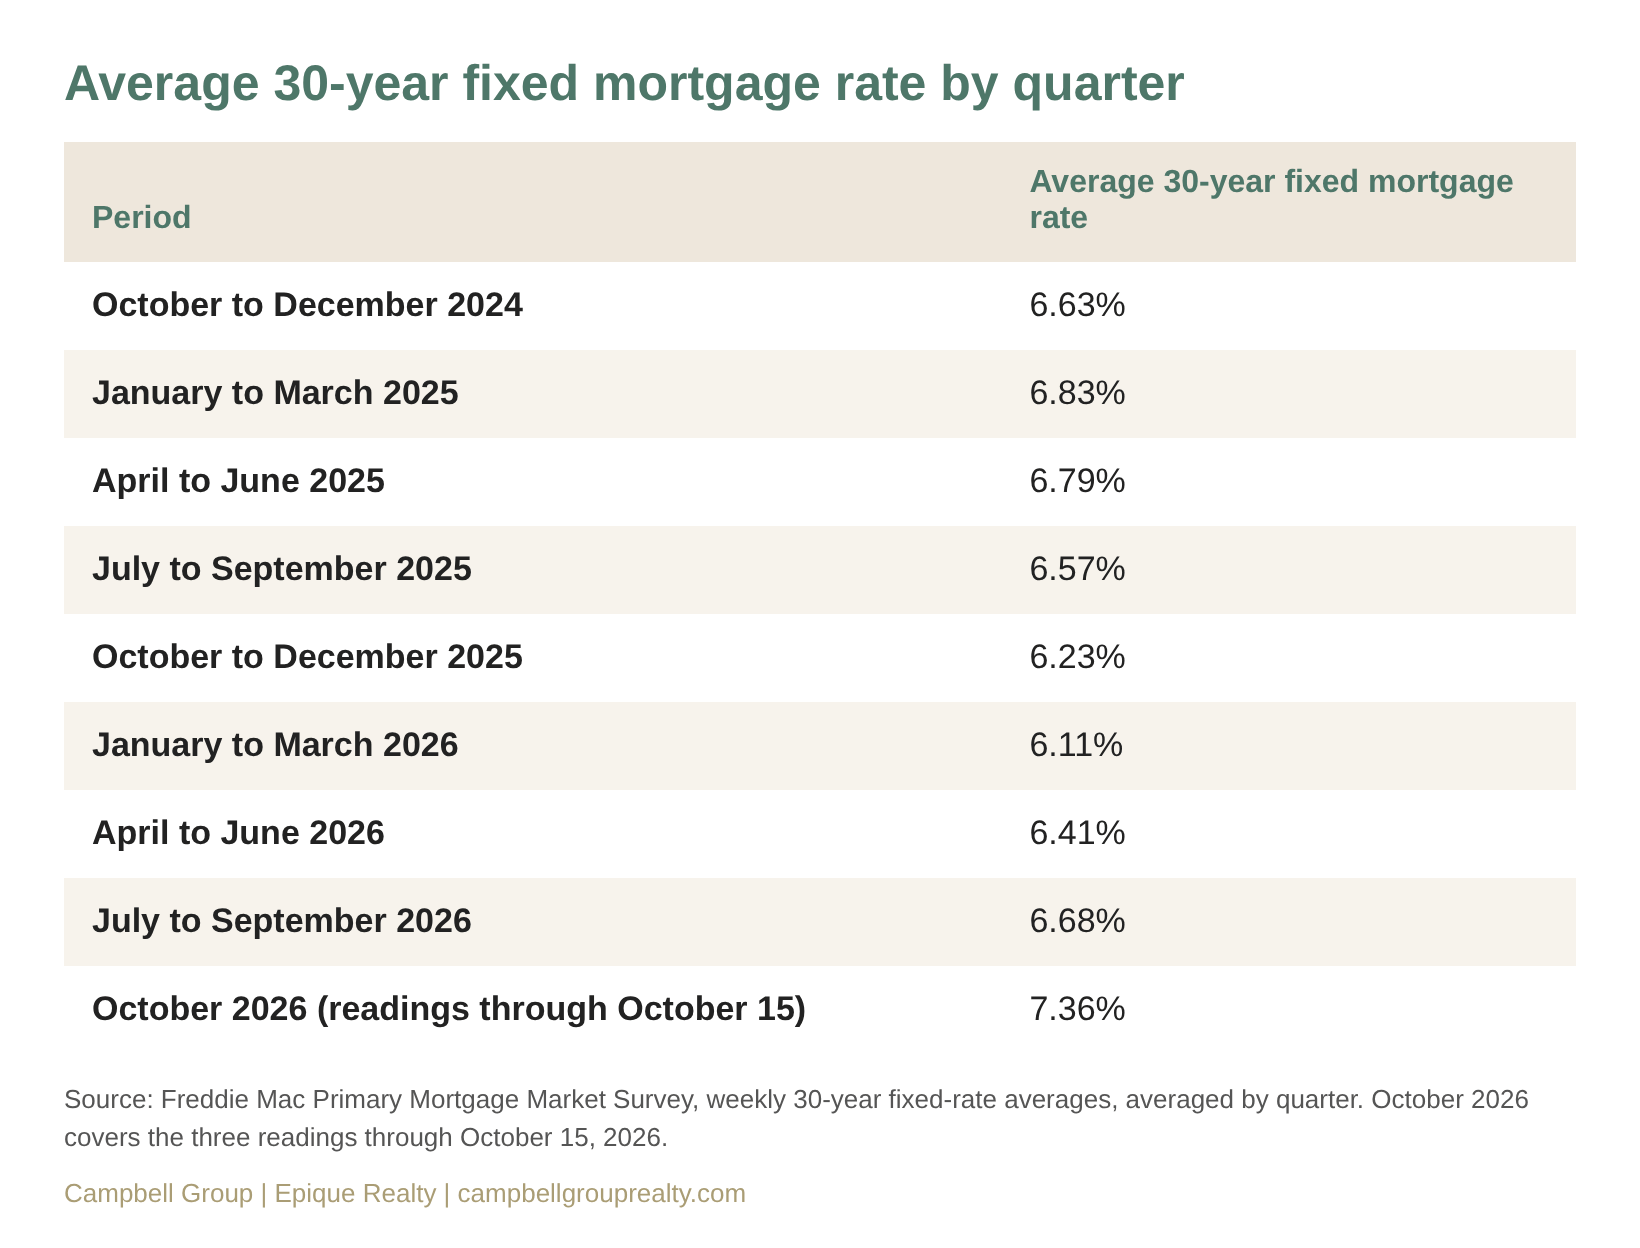
A rate change shows up in a monthly payment. Take a $300,000 loan on a 30-year fixed mortgage. At 6.27%, principal and interest comes to $1,851 a month. At 7.40%, that same loan would be $2,077 a month. That is $226 more each month, or about $2,700 a year, before property taxes and insurance. That is the clearest part of the cost of waiting, and it applies to anyone who finances.
Not everyone moving to a smaller home needs a mortgage. Some people buy with what they receive from selling their current home, and for them the rate does not affect their purchase. Even so, buyers of your home are looking at today's payments, so it is worth knowing where rates stand.
Putting It Together for Your Move
For someone moving to a smaller home, this is a market with choices and prices close to last year's, but with a higher rate. Nobody can say where rates go from here. They reached 7.04% in January 2025 and dipped just under 6% in February 2026, so they have moved a good deal in both directions.
The monthly cost of a home also includes property taxes, and a separate post shows how property taxes after 65 differ by county. For the longer view on timing, the complete guide to right-sizing in north metro Atlanta covers planning ahead, the move itself, and the market you would be moving into.
Looking at Your Own Numbers
If you would like to see the numbers for the area you are considering, I am happy to pull them for you. We can look at what similar homes are selling for and how quickly they sell, and discuss what that means for your timing. If you plan to finance, I can point you to a lender who can show you rate options for your situation.
Michelle Campbell | Campbell Group at Epique Realty | campbellgrouprealty.com
Categories
Recent Posts